
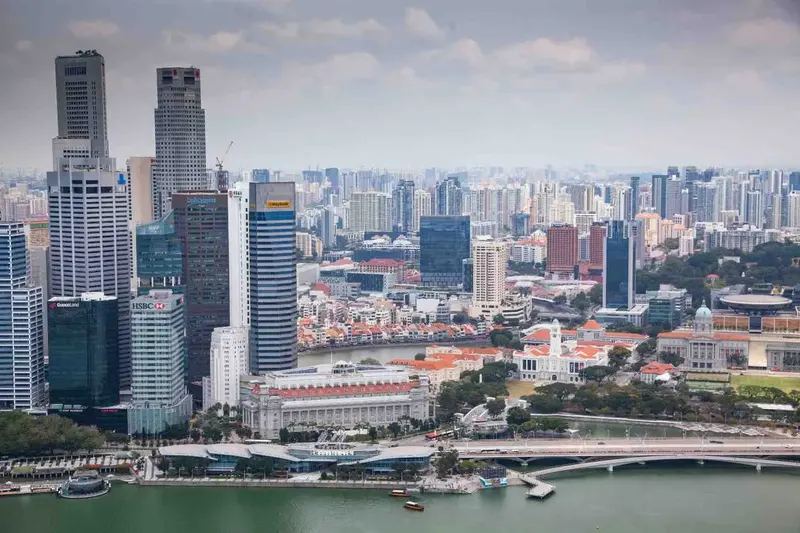
Singapore looks simple from the outside. Strong banks, global reputation, and a stable financial system. But once you actually try to open an account, the experience changes. Applications take longer. Questions go deeper. Requirements feel heavier than expected. This is not friction by accident. It is how the system is designed. Before deciding if Singapore banking is worth it, it helps to understand what you are really stepping into.
Related Reading: Top Singapore Banking Solutions for Individuals & Businesses
Why Singapore Banking Is Considered Premium
Singapore’s banking system is known for one thing above everything else: Stability.
That stability is not accidental. It is enforced by the Monetary Authority of Singapore, which regulates banks with strict compliance standards. Singapore’s financial services sector contributes over 13 percent of the country’s GDP. That alone shows how seriously the system is protected.
This creates a clear outcome. Banks here are designed to:
-
Protect capital
-
Maintain long-term trust
-
Avoid unnecessary risk
Once you are approved, the benefits are real:
-
Strong international credibility
-
Smooth cross-border transactions
-
Better perception with partners and institutions
But getting in is the hard part.
The Real Cost of Banking in Singapore
Most founders think cost means account fees or minimum balances. That is only the surface. The real cost is compliance.
Direct financial costs
These are the obvious ones:
-
Minimum deposits that can range from $50,000 to $200,000 depending on the bank
-
Monthly account maintenance fees
-
Transaction and foreign exchange charges
Compliance-driven costs
This is where things start to add up:
-
Preparing documentation that banks trust
-
Structuring your business correctly
-
Legal and advisory costs
Hidden operational costs
This is what most founders underestimate:
-
Delays in onboarding
-
Internal time spent answering compliance queries
-
Opportunity cost while waiting for approval
Cost Breakdown: What You See vs What You Don’t
| Cost Type | What You See | What You Don’t See |
|---|---|---|
| Bank Fees | Account fees, FX charges | Relationship expectations |
| Setup | Company formation | Structuring clarity required |
| Compliance | KYC forms | Continuous monitoring |
| Time | 2–4 weeks stated | Often 2–3 months actual |
Related Reading: Open a Singapore Bank Account for Foreigners: The Ultimate Guide
Why Compliance Is So Expensive
Singapore banks are not strict for no reason. They operate in one of the most advanced compliance environments globally. Compliance is no longer a simple process. It is an ongoing system. Banks must continuously monitor:
-
Customer identity and ownership
-
Transaction patterns
-
Cross-border activity
-
Exposure to sanctions, PEPs, and adverse media
Large financial institutions allocate around 4 to 7 percent of their operational budgets to compliance, with AML being the biggest contributor. That changes how banks behave. They are not trying to onboard more clients. They are trying to avoid the wrong ones.
The Hidden Problem: Too Many False Signals
Modern compliance systems flag large volumes of transactions. Many of them are not actually risky. This creates a problem for banks:
-
Too many alerts
-
Too much manual review
-
Too much operational burden
So banks respond in the simplest way possible. They filter harder at the start. Instead of dealing with complexity later, they avoid it upfront.
Did You Know
Singapore banks process large volumes of real-time transactions through systems like FAST and PayNow. This means transactions are monitored continuously, not just during onboarding. Compliance is not a one-time check—it is an ongoing process.
Source: https://www.mas.gov.sg/development/e-payments
What Banks Actually Evaluate
Most founders think banks evaluate where your company is registered. That is only part of it. Banks evaluate clarity. They want to understand your business quickly, without confusion.
What banks are looking for
-
A clear ownership structure
-
A defined business model
-
Predictable transaction flows
-
Logical connections between jurisdictions
What causes rejection
-
Complex ownership without explanation
-
Mismatch between business activity and structure
-
Incomplete or inconsistent documentation
-
High perceived compliance burden
Approval vs Rejection Signals
| Strong Approval Signals | Common Rejection Signals |
|---|---|
| Clear ownership chart | Unclear layered ownership |
| Defined revenue model | Vague or evolving business |
| Matching structure and activity | Random multi-country setup |
| Predictable transaction flow | High-risk unclear flows |
Is Singapore Banking Worth It
The answer depends on what you are optimizing for. Singapore is not the right fit for every business.
When Singapore Banking Makes Sense
| If You Need | Why Singapore Works |
|---|---|
| Global credibility | Strong international reputation with banks and partners |
| Banking stability | Low-risk environment with long-term reliability |
| Structured growth | Clear compliance framework for scaling |
| Asia-Pacific access | Strategic gateway to regional markets |
When Singapore May Not Be Ideal
| If You Need | Why It Becomes Challenging |
|---|---|
| Fast onboarding | Approval timelines can stretch to months |
| Low setup cost | Higher deposits, compliance, and advisory costs |
| Minimal compliance | Strict ongoing monitoring and reporting |
| High-risk flexibility | Low tolerance for unclear or complex risk profiles |
Singapore vs Practical Alternatives
Singapore is often compared to other jurisdictions, but the comparison is usually misunderstood.
Side-by-Side Comparison
| Factor | Singapore | Other Jurisdictions |
|---|---|---|
| Trust Level | Very high | Moderate to variable |
| Compliance Requirements | Strict | More flexible |
| Cost | Higher | Lower |
| Onboarding Speed | Slower | Faster |
| Long-term Stability | Strong | Depends on jurisdiction |
| Risk Tolerance | Low | Higher |
What This Actually Means
| Reality | Explanation |
|---|---|
| Singapore is not “better” | It is designed for control, not convenience |
| Other jurisdictions are not “worse” | They trade credibility for flexibility |
| The choice depends on your goals | Your business structure should match your banking needs |
How to Reduce Cost and Improve Approval Chances
Most of the cost in Singapore banking comes from getting it wrong the first time. A structured approach changes everything.
Start with a pre-assessment
Understand how your business will be evaluated before applying.
Align your structure with bank expectations
Do not build your structure first and try to justify it later.
Prepare documentation properly
This includes:
-
Clear business model explanation
-
Ownership breakdown
-
Transaction flow clarity
Choose the right bank
Not all banks accept the same risk profiles. Matching your business to the right institution is critical.
Most founders do not struggle with forming a company or submitting a bank application. The real challenge is making everything align in a way banks can understand quickly and confidently. That is where most applications break.
The Real Problem Is Not Banking. It Is Alignment
Banks are not evaluating effort. They are evaluating clarity. If your structure, documentation, and transaction logic do not align, the application creates friction. That friction turns into delays, additional questions, or outright rejection. Even strong businesses fail here because they are not presented in a way banks can process easily.
Our Approach: Make the Business Bankable First
What We Do Differently
We work on the parts that directly influence approval. We structure your business in a way that aligns with banking requirements. We match you with institutions that fit your specific risk profile. We identify and remove red flags before they become objections. We also prepare documentation in a way that banks can review without confusion or back-and-forth.
What This Changes
When everything is aligned before submission, the process becomes more predictable. Instead of delays and repeated queries, the application moves forward with clarity. Instead of uncertainty, you have a structured path. Instead of reactive fixes, issues are addressed before they appear. This reduces rejection risk, shortens timelines, and eliminates unnecessary cost.
The Outcome
Singapore banking is designed to filter risk. That does not change. What changes is how your business is positioned within that system. With the right structure and preparation, approval becomes a process, not a gamble.
No published comments yet.